Shake Shack Inc. (NYSE:SHAK) stock traded lower Thursday after the restaurant chain reported mixed third-quarter 2026 results. Earnings beat Wall Street estimates, but revenue fell short.
Despite the revenue miss, CEO Rob Lynch highlighted 2.5% same-Shack sales growth and a 0.8% increase in customer traffic, marking the fifth straight quarter of positive traffic growth.
However, Lynch warned that lower-income customers remain under pressure, particularly in urban markets. Stronger traffic from higher-income customers helped offset the weakness, allowing Shake Shack to maintain positive traffic growth despite a challenging consumer environment.
Shake Shack Beats Earnings Estimates, Misses Revenue
Shake Shack reported adjusted earnings of 40 cents per share, beating analysts’ estimate of 34 cents.
Revenue rose 15.2% year over year to $423.3 million, missing the $426.1 million estimate.
Net income attributable to Shake Shack increased to $16.5 million, or 39 cents per diluted share, from $12.5 million, or 30 cents per share.
Adjusted pro forma net income rose to $17.8 million from $15.9 million.
Shack sales increased 15.6% to $408 million, while licensing revenue grew 4.7% to $15.3 million.
Systemwide sales climbed 12.8% to $644.8 million.
The company opened 21 company-operated restaurants and 16 licensed locations during the quarter. Its global restaurant count reached 738.
Rapid Expansion Weighs on Average Weekly Sales
Average weekly sales fell 3.8% year over year to $75,000, partly reflecting the company’s rapid expansion.
Shake Shack reported 1.7% growth in price and sales mix, supported by roughly 4% gross pricing across its channels.
However, promotional offers and marketing investments pressured sales mix as the company worked to attract customers.
Shake Shack raised menu prices by another 1% in October to offset inflation.
Shake Shack Margins Narrow Despite Lower Food Costs
Restaurant-level profit rose 13.8% to $91.7 million. However, restaurant-level profit margin narrowed to 22.5% from 22.8%.
Food and paper costs improved to 28.3% of Shack sales from 29.3%. Lower bun, chicken and dairy costs helped offset elevated beef prices.
Labor expenses increased to 25.4% of Shack sales from 24.9%, while occupancy costs remained steady at 7.7%.
Adjusted EBITDA rose 16% to $62.8 million, representing a 14.8% margin.
Shake Shack ended September with $319 million in cash and cash equivalents, down from $360 million at the end of December.
Shake Shack Reaffirms 2026 Sales Outlook
Shake Shack maintained its fiscal 2026 sales forecast of $1.6 billion to $1.7 billion, compared with the $1.65 billion analyst estimate.
The company expects low-single-digit same-Shack sales growth and restaurant-level profit margins of 22% to 23%.
Management also highlighted digital engagement, menu innovation, loyalty programs and AI-powered tools as growth priorities.
Shake Shack continues to pursue its long-term goal of 1,500 company-operated restaurants.
SHAK Price Action: Shake Shack shares fell 3.45% to $70.31 at the time of publication Thursday, according to Benzinga Pro data.
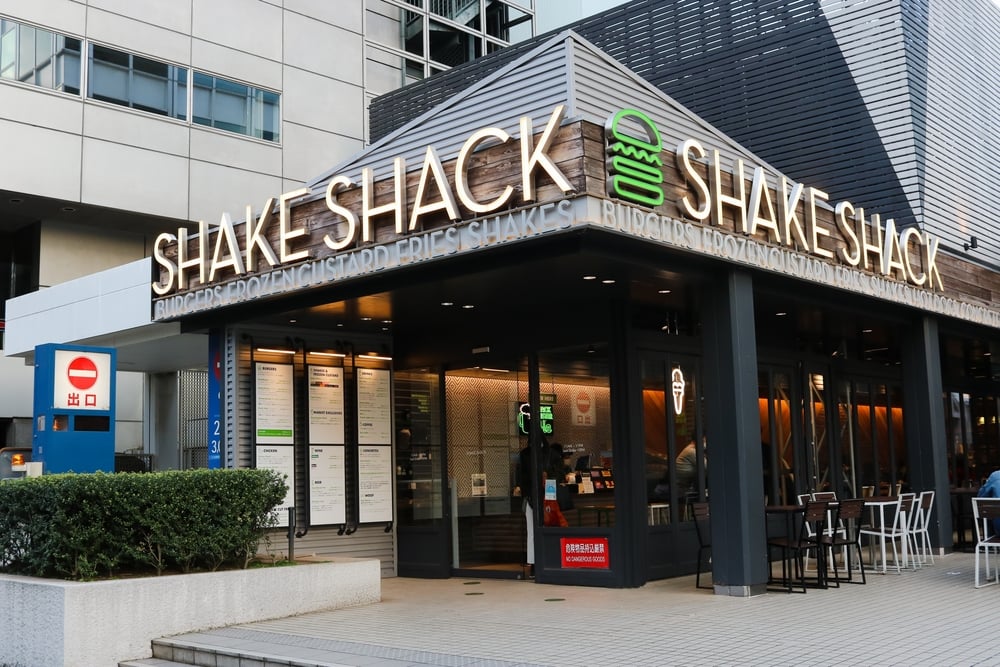
Image via Shutterstock