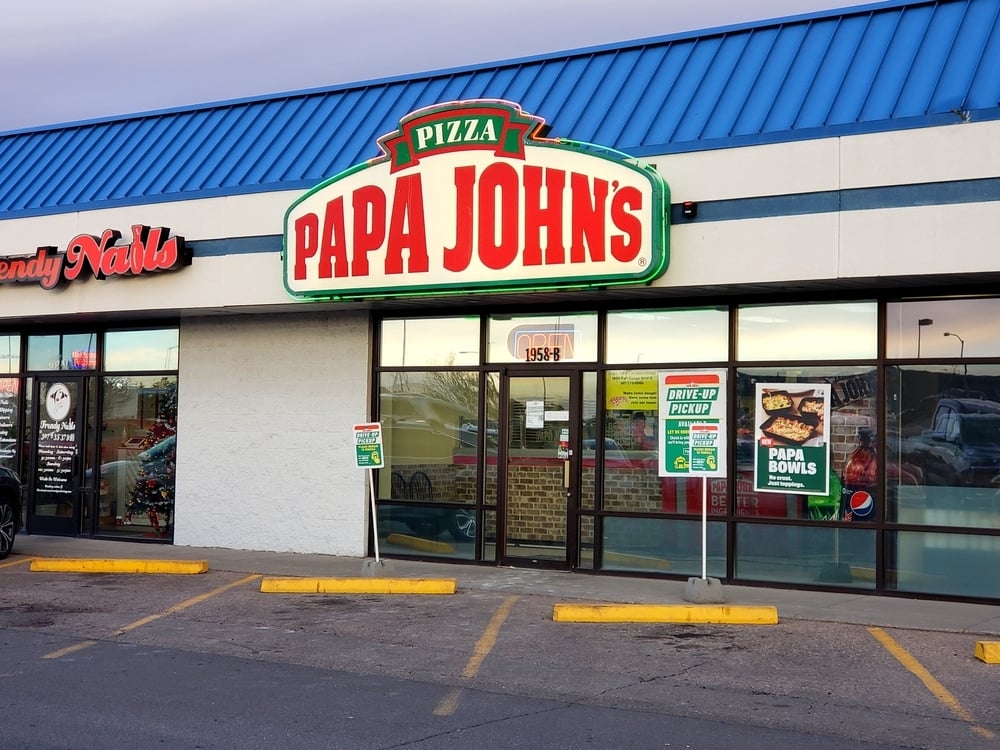
Papa John’s International Inc. (NASDAQ:PZZA) stock traded lower Thursday after the pizza chain reported weaker-than-expected third-quarter 2026 results and cut its full-year outlook.
Weak consumer demand, intense promotional competition and falling North American sales weighed on results.
Papa John’s Misses Earnings And Revenue Estimates
Papa John’s reported adjusted earnings of 16 cents per share, missing Wall Street’s estimate of 17 cents.
Revenue fell 10.5% year over year to $454.84 million, below the $459.48 million estimate.
North American comparable sales declined 8.3%, while global systemwide restaurant sales fell 5.6% to $1.15 billion.
Adjusted EBITDA dropped to $38.1 million from $47.8 million a year earlier.
Net income declined to $3.3 million from $4.5 million a year earlier. Free cash flow for the first nine months fell to $19.2 million from $59.2 million.
The company ended the quarter with $26.8 million in cash, cash equivalents and restricted cash.
North American Sales Face Pressure
CEO Todd Penegor cited aggressive promotions and weaker customer acquisition as major challenges.
Papa John’s said pressure on disposable income continues to affect how frequently consumers order pizza. Management also cited persistent weakness among lower-income consumers and intense competition in the pizza market, although it has not seen a dramatic shift in consumer behavior.
Carryout sales performed better than delivery. However, first-party delivery, single-pizza orders, sides and desserts remained weak.
International comparable sales declined 1.8%, although U.K. sales grew 7.2%.
Papa John’s opened 47 restaurants during the quarter, bringing its global total to 5,969 locations.
Papa John’s closed 239 restaurants worldwide during the first nine months of 2026, including 146 in North America. The company plans to close approximately 300 underperforming North American restaurants through 2027.
See More:
Top Value Stocks
Papa John’s Pushes Turnaround Strategy
Management introduced its Unbox Better strategy to improve food quality, customer value and restaurant service.
The company plans to increase local marketing investments and is already testing an AI-powered point-of-sale system. Papa John’s expects an initial rollout by year-end 2026, with most U.S. restaurants adopting the technology in 2027.
An initial rollout is expected by year-end 2026.
Papa John’s Cuts 2026 Outlook
Papa John’s now expects global systemwide restaurant sales to decline about 5%, compared with its previous forecast of a 2% to 4% decline.
Management forecasts North American comparable sales to fall approximately 8%. International comparable sales are expected to remain flat or grow up to 1%.
Papa John’s lowered its adjusted EBITDA forecast to approximately $175 million from its previous range of $180 million to $190 million. The revised outlook includes approximately $35 million in supplemental marketing and franchise investments.
It also forecasts at least $25 million in supply chain savings for 2026.
PZZA Price Action: Papa John’s International shares were down 2.33% at $19.52 at the time of publication on Thursday, according to Benzinga Pro data.
Image via Shutterstock