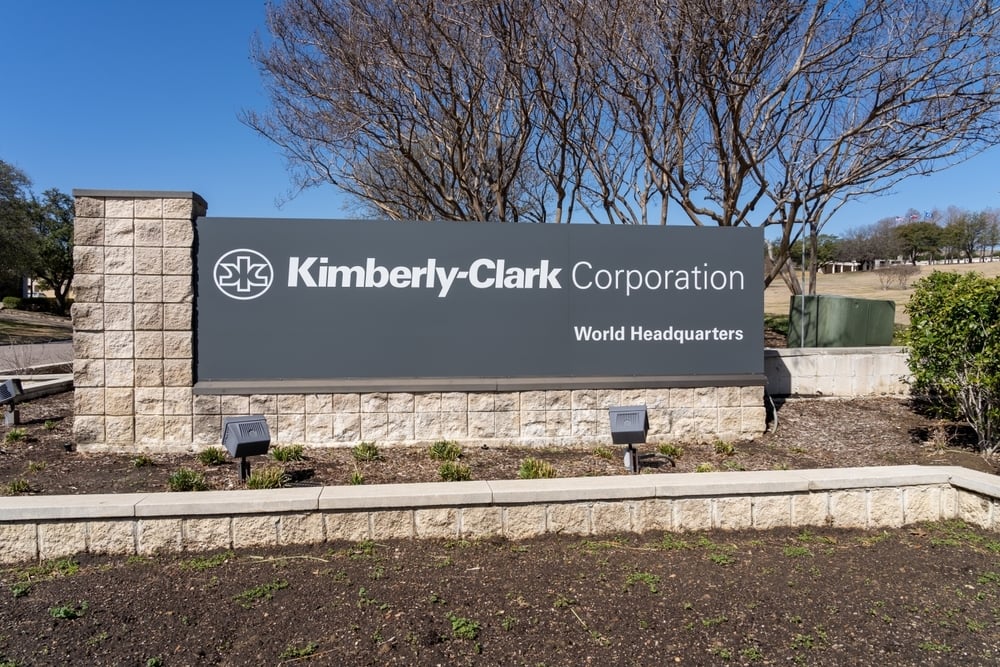
Kimberly-Clark Corp. (NASDAQ:KMB) stock traded higher Thursday after the company reported better-than-expected third-quarter 2026 results despite rising costs and continued market uncertainty.
The maker of Huggies and Kleenex reaffirmed its full-year standalone outlook, supported by strength in its North American tissue and personal care businesses.
Chairman and CEO Mike Hsu cited increased promotions, higher costs, retailer inventory changes and continued disruption in China’s diaper market as key challenges.
The results follow Kimberly-Clark’s acquisition of Kenvue, which the company said it completed Nov. 2. The deal marks a major push into consumer health and wellness.
Kimberly-Clark Beats Earnings Estimates
Kimberly-Clark reported adjusted earnings of $1.70 per share attributable to the company, beating Wall Street’s estimate of $1.64.
Revenue fell 0.4% year over year to $4.134 billion but exceeded analysts’ estimate of $4.126 billion.
Adjusted gross margin narrowed 130 basis points to 35.5%, reflecting pricing pressure, inflation and supply chain investments.
Adjusted operating profit fell 0.9% to $677 million.
See More:
Top Value Stocks
China Disruption Weighs on Sales
Organic sales declined 1.3%, including a 270-basis-point hit from social media-related disruption in China’s diaper market.
Kimberly-Clark said Chinese authorities found no evidence supporting the original allegations about its diaper products and confirmed their safety.
However, the controversy continues to hurt sales. Management warned that rebuilding consumer trust and restoring demand for Huggies in China will take time.
Retailer inventory changes in North America added pressure.
Management said the timing of a recovery in China remains uncertain. The company also postponed a North American product launch until 2027.
Kimberly-Clark expects $1.9 billion in cost synergies within three years through procurement savings, supply chain improvements and operational efficiencies.
North America Shows Resilience
North American revenue rose 0.9% to $2.7 billion, supported by Arbex joint venture transactions and 0.4% organic sales growth.
Volume and product mix increased 2.1%, offsetting a roughly 130-basis-point drag from retailer inventory changes.
International Personal Care revenue fell 2.8% to $1.4 billion.
Organic sales declined 4.6%, including a roughly 770-basis-point headwind from disruption in China’s diaper market. Growth in South Korea, Indonesia and other markets provided some relief.
Cash Flow Strengthens
Kimberly-Clark held $1.9 billion in cash and equivalents as of Sept. 30.
Operating cash flow for the first nine months rose to $2.4 billion from $1.8 billion a year earlier.
Capital spending totaled $1 billion, while dividend payments reached $1.3 billion.
Total debt from continuing operations declined to $6.5 billion from $7.2 billion at the end of 2025.
Kimberly-Clark Maintains 2026 Outlook
Kimberly-Clark expects 2026 organic sales growth to trail its 1.7% category growth benchmark by about 100 basis points, largely due to China-related challenges.
The company maintained its forecast for mid-single-digit adjusted operating profit growth on a constant-currency basis.
It also expects adjusted earnings per share from continuing operations to rise at a high single-digit rate.
However, adjusted earnings per share attributable to Kimberly-Clark are expected to decline by a low single-digit percentage on a constant-currency basis.
Management expects sustainable growth in 2027, supported by brand investments, category expansion and new growth opportunities.
KMB Price Action: Kimberly-Clark shares were up 2.68% at $111.70 at the time of publication on Thursday, according to Benzinga Pro data.
Image via Shutterstock